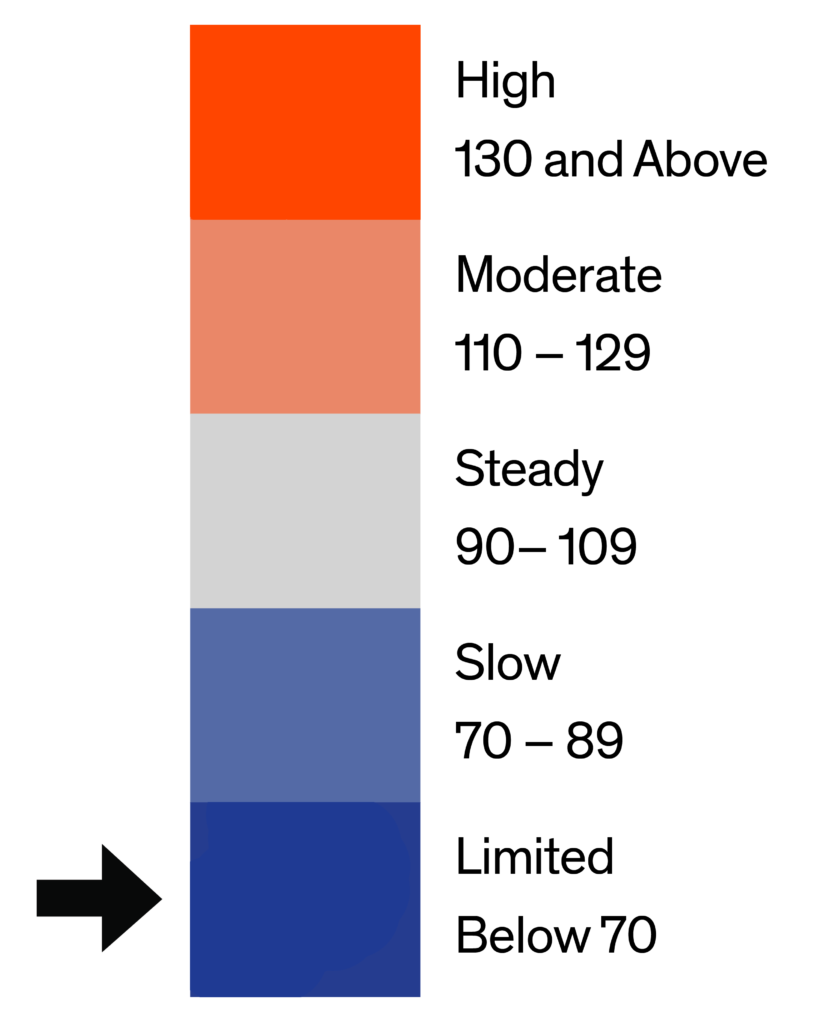Share report on Facebook!
Share on facebook
Share report on Twitter!
Share on twitter
Share report on LinkedIn!
Share on linkedin
Email a link to this Report!
Share on email
Download tile as an image.

Philadelphia | November 2026

Home Demand Index

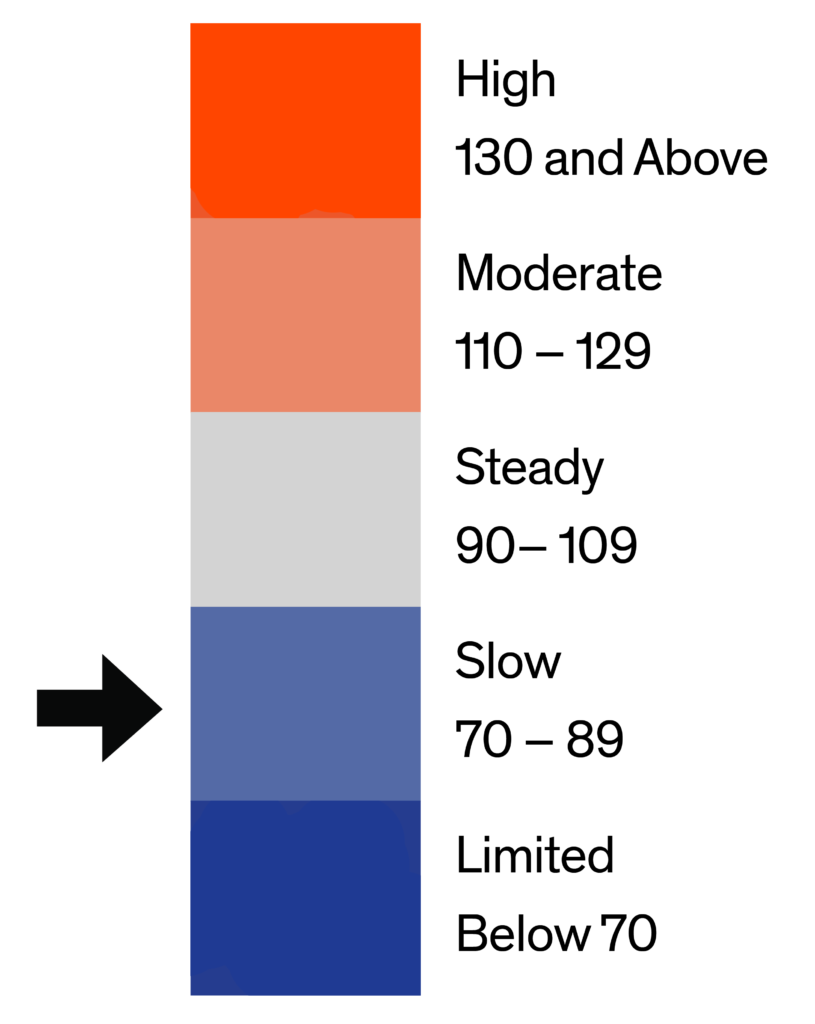
The Home Demand Index (HDI) for the Philadelphia metro area stands at 76 for this report period, down 3 points from last month’s 79 and below the 81 recorded one year ago. That leaves the market 3.8% lower on the month and 6.2% lower than a year ago, a milder cooling than in neighboring metros that keeps demand in Slow territory as the fall season winds down. All six home-type tiers eased on the month, though most moves were modest, pointing to a gradual seasonal slowdown rather than a sharp break.
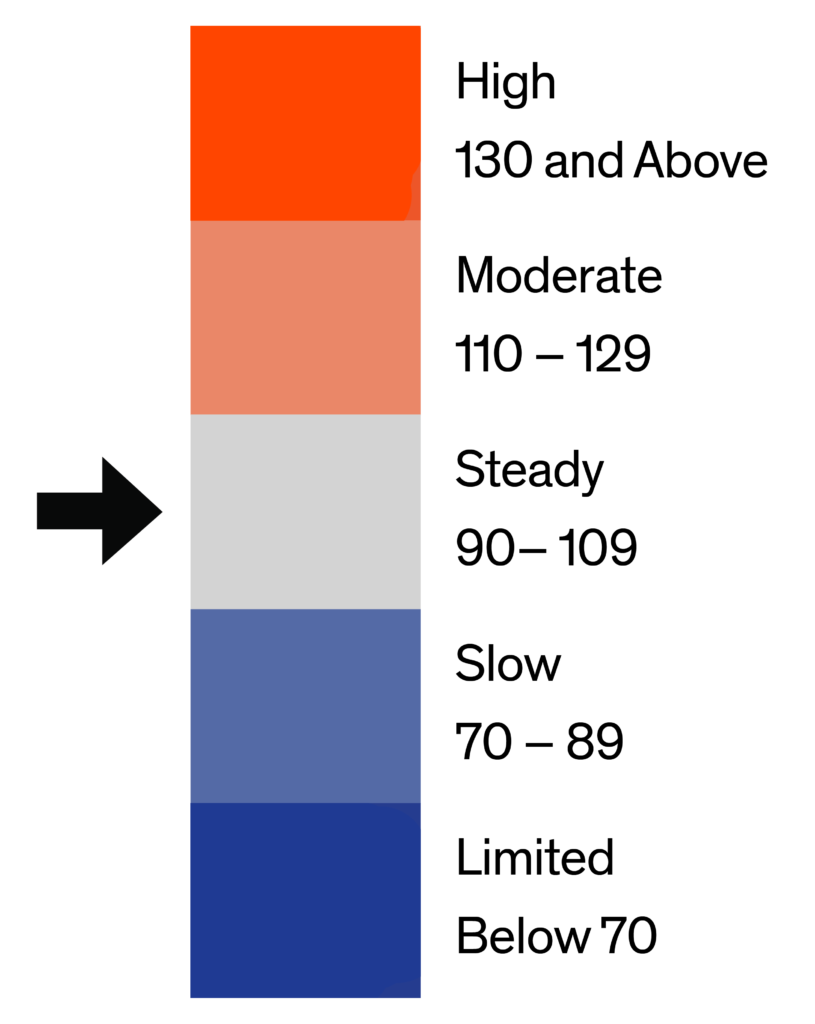
Demand by home type in Philadelphia this period ranges from a high of 105 in the luxury condo tier to a low of 63 in the luxury single-family tier, and every tier slipped on the month. Condos remain the strongest segment, with entry condos at 96 and luxury condos at 105, both Steady. Single-family demand is weaker: entry at 75 (Slow), mid-range at 68 and luxury at 63 (both Limited), although luxury single-family is the only tier above its year-ago level, up 1 point. The townhouse/rowhouse format, the metro’s highest-volume segment, reads 86. Inventory runs from about 2.6 months in mid-range single-family to 6.3 months in luxury condos.
Monthly Statistics for November 2026
Home Demand
Index
76
(Slow)
Home Demand Index
from prior month
79
Home Demand Index
from prior year
81
Index change
from prior month
-3.8%
Index change from
same time last year
-6.2%
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Download tile as an image.
Embed this tile on your site.

Philadelphia | November 2026

Home Demand Index | Historical Year-over-Year Comparison

Over the trailing twelve months, Philadelphia’s Home Demand Index traced its usual seasonal pattern, bottoming at 47 in December and climbing to a spring peak of 89 in April. Demand has eased gradually since, settling at 76 this period, below the prior-year path, which ran from 70 at the start of the window to 81 a year ago. The 5-point year-over-year gap is narrower than in Baltimore or Washington, suggesting Philadelphia’s demand is holding up comparatively well into the late fall.

Home Demand Index

Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Download the top-level Market Areas map as a screenshot.

Embed this tile on your site.

Philadelphia | November 2026

Home Demand Map

Demand across the Philadelphia metro spans a broad, multi-state footprint that includes Philadelphia, Bucks, Chester, Delaware and Montgomery counties in Pennsylvania; Burlington, Camden, Gloucester and Mercer counties in New Jersey; and Kent and New Castle counties in Delaware. That breadth produces wide local variation, with buyer activity strongest in Bucks, Kent and New Castle counties, where readings are in the Steady range, while the New Jersey counties show considerably weaker conditions, all falling in the Limited range. The remaining Pennsylvania counties range from Steady to Slow. The metro-wide Slow reading of 76 averages across these differing local conditions.
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Download tile as an image.
Embed this tile on your site.

Philadelphia | November 2026

Demand and Inventory by Home Type

Demand by home type in Philadelphia this period ranges from a high of 105 in the luxury condo tier to a low of 63 in the luxury single-family tier, and every tier slipped on the month. Condos remain the strongest segment, with entry condos at 96 and luxury condos at 105, both Steady. Single-family demand is weaker: entry at 75 (Slow), mid-range at 68 and luxury at 63 (both Limited), although luxury single-family is the only tier above its year-ago level, up 1 point. The townhouse/rowhouse format, the metro’s highest-volume segment, reads 86. Inventory runs from about 2.6 months in mid-range single-family to 6.3 months in luxury condos.
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Download tile as an image.

Philadelphia | November 2026

Single Family Home Below $375k

The index for entry-level single-family homes in Philadelphia (below $375,000) stands at 75 this report period, down 4 points from last month’s 79 and below the 83 recorded a year ago. That places the tier in Slow territory, with roughly 2.8 months of inventory across 1,622 active listings and 571 sales last month. Softer readings on both the monthly and annual comparisons point to demand running cooler than the same period last cycle at this price point.
Monthly Statistics for Single Family Home Below $375k
Home Demand
Index
75
(Slow)
Home Demand Index
from prior month
79
Home Demand Index
from prior year
83
Months of
inventory
2.8
Average daily inventory last month
1,622
Inventory sold
last month
571
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Download tile as an image.

Philadelphia | November 2026

Single Family Home $375k - $825k

The index for mid-range single-family homes in Philadelphia ($375,000 to $825,000) stands at 68 this report period, down 3 points from last month’s 71 and below the 74 recorded a year ago. That places the tier in Limited territory, with roughly 2.6 months of inventory across 3,928 active listings and 1,503 sales last month. Softer readings on both the monthly and annual comparisons point to demand running cooler than the same period last cycle at this price point.
Monthly Statistics for Single Family Home $375k - $825k
Home Demand
Index
68
(Limited)
Home Demand Index
from prior month
71
Home Demand Index
from prior year
74
Months of
Inventory
2.6
Average daily inventory last month
3,928
Inventory sold
last month
1,503
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Download tile as an image.

Philadelphia | November 2026

Single Family Home Above $825k

The index for luxury single-family homes in Philadelphia (above $825,000) stands at 63 this report period, down 4 points from last month’s 67 and above the 62 recorded a year ago. That places the tier in Limited territory, with roughly 4.0 months of inventory across 1,388 active listings and 351 sales last month. Demand at this price point is holding up relative to last year.
Monthly Statistics for Single Family Home Above $825k
Home Demand
Index
63
(Limited)
Home Demand Index
from prior month
67
Home Demand Index
from prior year
62
Months of
Inventory
4.0
Average daily inventory last month
1,388
Inventory sold
last month
351
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Download tile as an image.

Philadelphia | November 2026

Condo Below $435k

The index for entry-level condominium homes in Philadelphia (below $435,000) stands at 96 this report period, down 2 points from last month’s 98 and below the 111 recorded a year ago. That places the tier in Steady territory, with roughly 5.2 months of inventory across 1,268 active listings and 245 sales last month. Softer readings on both the monthly and annual comparisons point to demand running cooler than the same period last cycle at this price point.
Monthly Statistics for Condo Below $435k
Home Demand
Index
96
(Steady)
Home Demand Index
from prior month
98
Home Demand Index
from prior year
111
Months of
Inventory
5.2
Average daily inventory last month
1,268
Inventory sold
last month
245
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

This is Tooltip!

Philadelphia | November 2026

Condo Above $435k

The index for luxury condominium homes in Philadelphia (above $435,000) stands at 105 this report period, down 6 points from last month’s 111 and below the 111 recorded a year ago. That places the tier in Steady territory, with roughly 6.3 months of inventory across 309 active listings and 49 sales last month. Softer readings on both the monthly and annual comparisons point to demand running cooler than the same period last cycle at this price point.
Monthly Statistics for Condo Above $435k
Home Demand
Index
105
(Steady)
Home Demand Index
from prior month
111
Home Demand Index
from prior year
111
Months of
Inventory
6.3
Average daily inventory last month
309
Inventory sold
last month
49
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

This is Tooltip!

Philadelphia | November 2026

Townhouse/Rowhouse/Twin All prices

Townhouse/
Rowhouse/Twin
All prices

The index for townhouses, rowhouses and twins in Philadelphia (all prices) stands at 86 this report period, down 2 points from last month’s 88 and below the 90 recorded a year ago. The tier sits in Slow territory with about 4.8 months of inventory across 8,271 active listings and 1,725 sales last month. As the metro’s highest-volume attached format, it typically tracks close to the overall market, and this period it reads 86 against the metro’s 76.
Monthly Statistics for Townhouse/Rowhouse/TwinAll prices
Home Demand
Index
86
(Slow)
Home Demand Index
from prior month
88
Home Demand Index
from prior year
90
Months of
Inventory
4.8
Average daily inventory last month
8,271
Inventory sold
last month
1,725
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Note

1. This report is generated with data from the following counties:
  • Central Pennsylvania – Adams, PA; Berks, PA; Cumberland, PA; Dauphin, PA; Franklin, PA; Fulton, PA; Lancaster, PA; Lebanon, PA; Perry, PA; Schuylkill, PA; York, PA;
  • Ocean County – Ocean, NJ;
  • Philadelphia Metro – Bucks, PA; Burlington, NJ; Camden, NJ; Chester, PA; Delaware, PA; Gloucester, NJ; Kent, DE; Mercer, NJ; Montgomery, PA; New Castle, DE; Philadelphia, PA;
  • Salem-Cumberland – Cumberland, NJ; Salem, NJ;
2. This report is for the November 2026 period with data collected from the previous month.
Released: November 11, 2026
Reference ID: 2527

Philadelphia | November 2026

Home Demand Map (Zip Codes)

Demand across the Philadelphia metro spans a broad, multi-state footprint that includes Philadelphia, Bucks, Chester, Delaware and Montgomery counties in Pennsylvania; Burlington, Camden, Gloucester and Mercer counties in New Jersey; and Kent and New Castle counties in Delaware. That breadth produces wide local variation, with buyer activity strongest in Bucks, Kent and New Castle counties, where readings are in the Steady range, while the New Jersey counties show considerably weaker conditions, all falling in the Limited range. The remaining Pennsylvania counties range from Steady to Slow. The metro-wide Slow reading of 76 averages across these differing local conditions.
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Embed the Timeline

To embed the map on your website, copy and paste the code below. Please note that the ideal dimensions for displaying the map are 1312 pixels wide by 660 pixels high.

Embed the Map

To embed the map on your website, copy and paste the code below. Please note that the ideal dimensions for displaying the map are 1312 pixels wide by 1182 pixels high.

Embed the Housing Type Bar Chart

To embed the map on your website, copy and paste the code below. Please note that the ideal dimensions for displaying the map are 1312 pixels wide by 880 pixels high.