Share report on Facebook!
Share on facebook
Share report on Twitter!
Share on twitter
Share report on LinkedIn!
Share on linkedin
Email a link to this Report!
Share on email
Download tile as an image.

Baltimore | November 2026

Home Demand Index

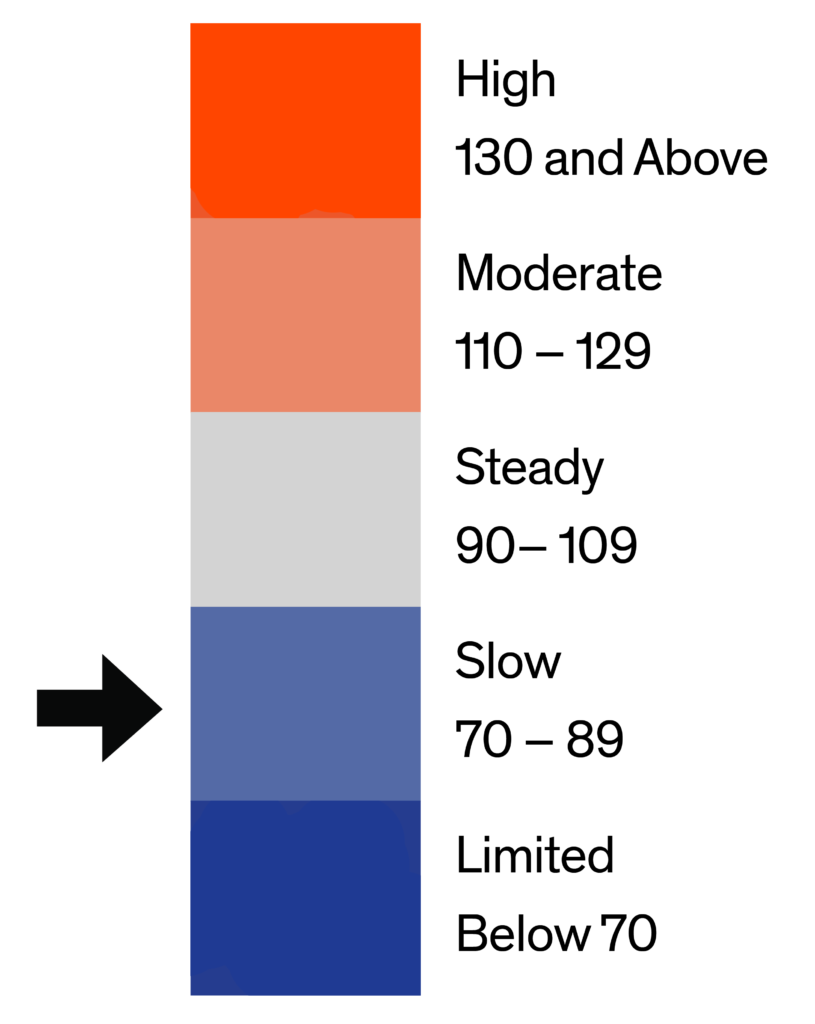
The Home Demand Index (HDI) for the Baltimore metro area stands at 78 for this report period, down 5 points from last month’s 83 and below the 89 recorded one year ago. That leaves the market 6.0% lower on the month and 12.4% lower than a year ago, extending the fall cooling and keeping a Slow demand rating as the market heads toward its seasonal winter low. The softening is broad: all six home-type tiers eased on the month, which points to a metro-wide seasonal and affordability-driven pullback rather than a shift in any single segment.
Demand by home type in Baltimore this period ranges from a high of 108 in the luxury condo tier to a low of 73 in the entry single-family tier, and every tier declined on the month. The condo tiers still screen strongest, with entry condos at 102 and luxury condos at 108, both Steady, though luxury condo demand is down 53 points from an unusually strong reading a year ago. Single-family demand sits lower across all three price bands: entry at 73, mid-range at 76 and luxury at 78, the last down 22 points year over year, all rated Slow. The townhouse/rowhouse format reads 82, down 7 points on the month. Inventory runs from about 3.3 months in mid-range single-family to 5.6 months in luxury condos, leaving the metro balanced-to-soft rather than tight.
Monthly Statistics for November 2026
Home Demand
Index
78
(Slow)
Home Demand Index
from prior month
83
Home Demand Index
from prior year
89
Index change
from prior month
-6.0%
Index change from
same time last year
-12.4%
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Download tile as an image.
Embed this tile on your site.

Baltimore | November 2026

Home Demand Index | Historical Year-over-Year Comparison

Over the trailing twelve months, Baltimore’s Home Demand Index followed its familiar seasonal arc, falling to a low of 57 in December before recovering to a spring peak of 94 in April. It has since drifted lower through the summer and fall to the current 78, below the prior-year path, which ran from 75 at the start of the window to 89 a year ago. The 11-point year-over-year gap is the widest since the late-spring months, underscoring that this fall’s demand is running noticeably cooler than the comparable stretch of 2025.

Home Demand Index

Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Download the top-level Market Areas map as a screenshot.

Embed this tile on your site.

Baltimore | November 2026

Home Demand Map

Demand across the Baltimore metro continues to reflect its established geographic structure, spanning Anne Arundel, Baltimore City, Baltimore County, Carroll, Harford and Howard counties. Buyer activity remains strongest in Howard, Harford and Baltimore counties, while Baltimore City and Carroll County show weaker demand, reflecting a clear divergence across the metro’s submarkets. The overall Slow reading of 78 masks that internal variation, with individual submarkets sitting on either side of the metro average.
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Download tile as an image.
Embed this tile on your site.

Baltimore | November 2026

Demand and Inventory by Home Type

Demand by home type in Baltimore this period ranges from a high of 108 in the luxury condo tier to a low of 73 in the entry single-family tier, and every tier declined on the month. The condo tiers still screen strongest, with entry condos at 102 and luxury condos at 108, both Steady, though luxury condo demand is down 53 points from an unusually strong reading a year ago. Single-family demand sits lower across all three price bands: entry at 73, mid-range at 76 and luxury at 78, the last down 22 points year over year, all rated Slow. The townhouse/rowhouse format reads 82, down 7 points on the month. Inventory runs from about 3.3 months in mid-range single-family to 5.6 months in luxury condos, leaving the metro balanced-to-soft rather than tight.
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Download tile as an image.

Baltimore | November 2026

Single Family Home Below $380k

The index for entry-level single-family homes in Baltimore (below $380,000) stands at 73 this report period, down 1 point from last month’s 74 and below the 77 recorded a year ago. That places the tier in Slow territory, with roughly 3.9 months of inventory across 897 active listings and 231 sales last month. Softer readings on both the monthly and annual comparisons point to demand running cooler than the same period last cycle at this price point.
Monthly Statistics for Single Family Home Below $380k
Home Demand
Index
73
(Slow)
Home Demand Index
from prior month
74
Home Demand Index
from prior year
77
Months of
inventory
3.9
Average daily inventory last month
897
Inventory sold
last month
231
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Download tile as an image.

Baltimore | November 2026

Single Family Home $380k - $875k

The index for mid-range single-family homes in Baltimore ($380,000 to $875,000) stands at 76 this report period, down 4 points from last month’s 80 and below the 88 recorded a year ago. That places the tier in Slow territory, with roughly 3.3 months of inventory across 2,031 active listings and 617 sales last month. Softer readings on both the monthly and annual comparisons point to demand running cooler than the same period last cycle at this price point.
Monthly Statistics for Single Family Home $380k - $875k
Home Demand
Index
76
(Slow)
Home Demand Index
from prior month
80
Home Demand Index
from prior year
88
Months of
Inventory
3.3
Average daily inventory last month
2,031
Inventory sold
last month
617
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Download tile as an image.

Baltimore | November 2026

Single Family Home Above $875k

The index for luxury single-family homes in Baltimore (above $875,000) stands at 78 this report period, down 7 points from last month’s 85 and below the 100 recorded a year ago. That places the tier in Slow territory, with roughly 3.9 months of inventory across 611 active listings and 157 sales last month. Softer readings on both the monthly and annual comparisons point to demand running cooler than the same period last cycle at this price point.
Monthly Statistics for Single Family Home Above $875k
Home Demand
Index
78
(Slow)
Home Demand Index
from prior month
85
Home Demand Index
from prior year
100
Months of
Inventory
3.9
Average daily inventory last month
611
Inventory sold
last month
157
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Download tile as an image.

Baltimore | November 2026

Condo Below $419k

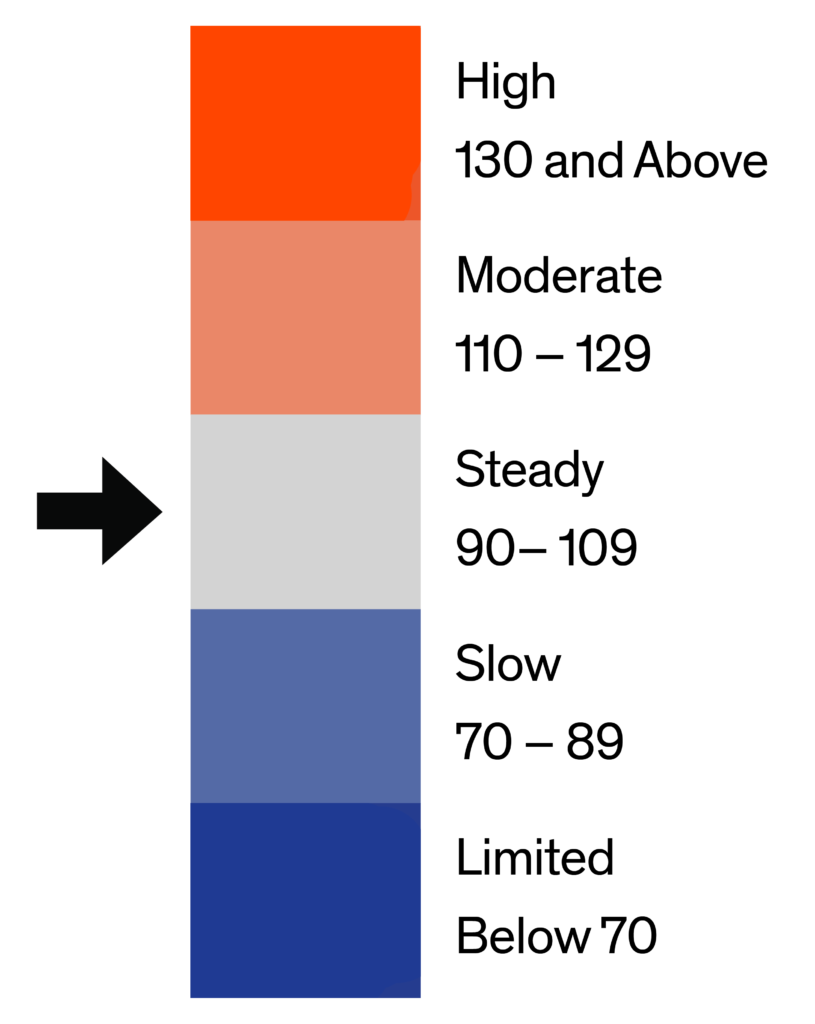
The index for entry-level condominium homes in Baltimore (below $419,000) stands at 102 this report period, down 11 points from last month’s 113 and below the 109 recorded a year ago. That places the tier in Steady territory, with roughly 5.0 months of inventory across 700 active listings and 141 sales last month. Softer readings on both the monthly and annual comparisons point to demand running cooler than the same period last cycle at this price point.
Monthly Statistics for Condo Below $419k
Home Demand
Index
102
(Steady)
Home Demand Index
from prior month
113
Home Demand Index
from prior year
109
Months of
Inventory
5.0
Average daily inventory last month
700
Inventory sold
last month
141
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

This is Tooltip!

Baltimore | November 2026

Condo Above $419k

The index for luxury condominium homes in Baltimore (above $419,000) stands at 108 this report period, down 14 points from last month’s 122 and below the 161 recorded a year ago. That places the tier in Steady territory, with roughly 5.6 months of inventory across 140 active listings and 25 sales last month. Softer readings on both the monthly and annual comparisons point to demand running cooler than the same period last cycle at this price point.
Monthly Statistics for Condo Above $419k
Home Demand
Index
108
(Steady)
Home Demand Index
from prior month
122
Home Demand Index
from prior year
161
Months of
Inventory
5.6
Average daily inventory last month
140
Inventory sold
last month
25
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

This is Tooltip!

Baltimore | November 2026

Townhouse/Rowhouse/Twin All prices

Townhouse/
Rowhouse/Twin
All prices

The index for townhouses, rowhouses and twins in Baltimore (all prices) stands at 82 this report period, down 7 points from last month’s 89 and below the 93 recorded a year ago. The tier sits in Slow territory with about 5.1 months of inventory across 3,979 active listings and 778 sales last month. As the metro’s highest-volume attached format, it typically tracks close to the overall market, and this period it reads 82 against the metro’s 78.
Monthly Statistics for Townhouse/Rowhouse/TwinAll prices
Home Demand
Index
82
(Slow)
Home Demand Index
from prior month
89
Home Demand Index
from prior year
93
Months of
Inventory
5.1
Average daily inventory last month
3,979
Inventory sold
last month
778
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Note

1. This report is generated with data from the following counties:
  • Baltimore Metro – Anne Arundel, MD; Baltimore City, MD; Baltimore, MD; Carroll, MD; Harford, MD; Howard, MD;
  • DelMar Coastal – Somerset, MD; Sussex, DE; Wicomico, MD; Worcester, MD;
  • Maryland Eastern Shore – Caroline, MD; Cecil, MD; Dorchester, MD; Kent, MD; Queen Annes, MD; Talbot, MD;
2. This report is for the November 2026 period with data collected from the previous month.
Released: November 11, 2026
Reference ID: 2526

Baltimore | November 2026

Home Demand Map (Zip Codes)

Demand across the Baltimore metro continues to reflect its established geographic structure, spanning Anne Arundel, Baltimore City, Baltimore County, Carroll, Harford and Howard counties. Buyer activity remains strongest in Howard, Harford and Baltimore counties, while Baltimore City and Carroll County show weaker demand, reflecting a clear divergence across the metro’s submarkets. The overall Slow reading of 78 masks that internal variation, with individual submarkets sitting on either side of the metro average.
Bright MLS | T3 Home Demand Index

www.homedemandindex.com

Embed the Timeline

To embed the map on your website, copy and paste the code below. Please note that the ideal dimensions for displaying the map are 1312 pixels wide by 660 pixels high.

Embed the Map

To embed the map on your website, copy and paste the code below. Please note that the ideal dimensions for displaying the map are 1312 pixels wide by 1182 pixels high.

Embed the Housing Type Bar Chart

To embed the map on your website, copy and paste the code below. Please note that the ideal dimensions for displaying the map are 1312 pixels wide by 880 pixels high.